Trending...
- Colorado: What Pueblo Leaders Are Saying About the Pueblo Chile 2028 American Innovation Coin
- Building a Diversified Healthcare Platform as Exosome Science, Telehealth, Diagnostics & Strategic Acquisitions Converge: NexTel Medical (OTCID: MAJI)
- Mom Era, Still That Girl: Family Art Tees 25% Off
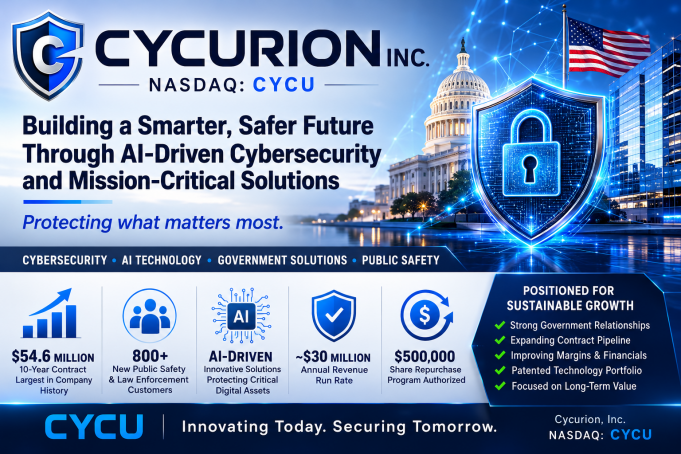
~$30 Million Revenue Run Rate, 800+ New Public-Safety Customers, New Patents and $500,000 Share Repurchase Program Highlight a Dramatic 2026 Transformation
MCLEAN, Va. - ColoradoDesk -- Cycurion, Inc. (N a s d a q: CYCU) has continued to build significant momentum as it moves through the second half of 2026, with a series of developments that increasingly position the company as a broader AI-driven cybersecurity, public-safety and managed-services technology platform.
Since the company's strong second-quarter results, CYCU has added additional intellectual property, completed its Digital Ally acquisition, announced a $500,000 share repurchase authorization, implemented a 1-for-8 reverse stock split, and continued pursuing a substantial government-contract pipeline.
Perhaps most importantly for investors, the company's underlying financial profile is improving dramatically. Second-quarter gross margin reached 29.1%, compared with just 6.1% a year earlier, while management says the combination of acquisitions and new contracts has moved the company's annualized revenue run rate toward approximately $30 million.
Key Investor Highlights
The Share Buyback Remains a Major Signal
One of the more interesting developments for shareholders was Cycurion's August 17 announcement authorizing a $500,000 share repurchase program over the following 12 months.
Management stated that it believes Cycurion is "meaningfully undervalued" relative to the business it has built and its trajectory. Repurchases can be made in open-market transactions or other lawful methods, although they remain subject to market conditions, liquidity, financing restrictions and CFO approval. The company is not obligated to repurchase any specific amount.
It is important to distinguish this from insider buying. The $500,000 authorization is a corporate share-repurchase program, not necessarily an executive personally purchasing shares.
After reviewing the recent SEC-related ownership information available for CYCU, I do not find evidence of a new significant open-market insider purchase by a Cycurion executive or director in August. Recent filings include new officer ownership disclosures, but those do not themselves report a purchase transaction.
More on Colorado Desk
So, while there is currently a strong management confidence/buyback story, investors should not confuse that with a newly reported insider Form 4 purchase.
Q2 Financial Results Show the Margin Story Is Getting Real
Cycurion's August 14 financial results remain one of the most important developments of the year.
The company reported:
$3.8 million in Q2 revenue, beating Wall Street's $3.62 million consensus, while gross profit increased to $1.1 million. The resulting 29.1% gross margin was nearly five times the 6.1% margin reported in Q2 2025.
EPS of $(0.41) also beat the consensus estimate of $(0.56), net loss improved to $4.0 million from $5.3 million, and adjusted EBITDA loss improved to $1.4 million from $2.1 million. Net debt declined 28% year-over-year to $5.8 million.
For investors, that margin expansion could ultimately be more important than the relatively flat year-over-year revenue.
Cycurion is deliberately shifting toward higher-margin cybersecurity, managed services and strategic consulting, and management believes the financial results are beginning to demonstrate the benefits of that strategy.
The $54.6 Million Contract Remains a Game Changer
CYCU's largest contract ever remains another major pillar of the investment story.
The company secured a $54.6 million, 10-year award through a partnership with a Top-5 global consulting firm to modernize and securely operate a major state Health and Human Services system.
The contract is expected to generate more than $5 million in annual revenue, with work scheduled to begin in November 2026.
A decade-long agreement of this size gives CYCU considerably more revenue visibility and could also create opportunities for additional business with the agency and consulting partner.
Digital Ally Is More Than an Acquisition
The August 4 closing of the Digital Ally video-solutions acquisition significantly broadened Cycurion's reach.
The acquired business adds more than $5 million of annual revenue and over $1.2 million of EBITDA, while bringing more than 800 law-enforcement, municipal and public-safety customers into CYCU's ecosystem.
The strategic opportunity is the cross-selling potential.
These customers already depend on Digital Ally's video and evidence-management products. Cycurion can potentially add cybersecurity, managed services and other technology solutions around those systems.
The acquisition also brought a portfolio of 50+ patents, strengthening CYCU's position in video surveillance, digital evidence and public-safety technology.
New Patents Expand the Addressable Market
Cycurion has continued building its intellectual-property portfolio since the acquisition.
On August 18, the company announced a new patent covering fleet driver analytics, designed to track vehicles, connect incidents with video evidence and generate comparative driver-performance profiles. CYCU says the technology gives it an opportunity to pursue commercial trucking, logistics, delivery and corporate fleets in addition to its existing public-safety market.
More on Colorado Desk
On August 19, the company announced another patent strengthening its VuLink technology, which automatically activates and synchronizes multiple recording devices—including body cameras and vehicle cameras—during an incident.
Together, these developments potentially make the Digital Ally platform more valuable to CYCU's existing 800+ customer relationships while opening additional commercial markets.
Reverse Split and Nasdaq Situation
Cycurion also implemented a 1-for-8 reverse stock split, effective August 28, 2026, with the shares beginning split-adjusted trading under the existing CYCU symbol.
Management has described the move as a step intended to address Nasdaq's minimum-bid requirement rather than a change to the underlying business.
In its shareholder letter, CEO Kevin Kelly emphasized that the company's focus remains on expanding margins, reducing debt, growing government and commercial relationships and ultimately reaching break-even, profitability and a cash-positive operating position by Q2 2027.
A Growing Pipeline Adds Another Layer of Potential
The company's opportunity pipeline remains significant.
As of early August, CYCU reported 122 open opportunities representing approximately $34 million in potential first-year contract value, including approximately $11 million in late-stage opportunities. The company had already closed 41 new awards during 2026.
That pipeline, combined with the $54.6 million contract, Digital Ally acquisition and expanding public-sector relationships, gives CYCU considerably more forward visibility than it had at the beginning of the year.
The Bottom Line for Investors
Cycurion is becoming an increasingly interesting story because multiple pieces are improving at the same time.
The company is not simply adding revenue. It is attempting to improve margins, acquire EBITDA-producing businesses, build recurring government relationships, expand its intellectual property and cross-sell cybersecurity into a much larger installed customer base.
The $500,000 buyback authorization adds a noteworthy vote of confidence from the Board, although investors should understand that it is not the same thing as new insider open-market buying.
Meanwhile, the 29.1% gross margin, $54.6 million 10-year contract, ~$30 million revenue run rate, 800+ new public-safety customers, 50+ patents and $34 million potential contract pipeline provide CYCU with a substantially broader story heading into the final months of 2026.
The next major test is execution: converting the pipeline into revenue, integrating acquisitions, maintaining margin expansion, reducing losses and ultimately reaching the profitability target management has established.
For investors willing to follow a speculative small-cap cybersecurity company through that execution phase, $CYCU has certainly become a company worth watching closely.
For more information on $CYCU visit: www.cycurion.com
Media Contact:
Company Name: Cycurion, Inc. (N a s d a q: CYCU)
Contact: Kevin Kelly, Chairman & CEO
Email: info@cycurion.com
Phone: 888-341-6680
Country: United States
DISCLAIMER: https://corporateads.com/disclaimer/
Disclosure listed on the CorporateAds website
Since the company's strong second-quarter results, CYCU has added additional intellectual property, completed its Digital Ally acquisition, announced a $500,000 share repurchase authorization, implemented a 1-for-8 reverse stock split, and continued pursuing a substantial government-contract pipeline.
Perhaps most importantly for investors, the company's underlying financial profile is improving dramatically. Second-quarter gross margin reached 29.1%, compared with just 6.1% a year earlier, while management says the combination of acquisitions and new contracts has moved the company's annualized revenue run rate toward approximately $30 million.
Key Investor Highlights
- $54.6 million, 10-year contract — the largest contract in CYCU history
- Approximately $30 million annual revenue run rate
- 29.1% Q2 gross margin, up from 6.1% year-over-year
- $500,000 share repurchase program authorized over 12 months
- Digital Ally acquisition adds $5M+ revenue and $1.2M+ EBITDA
- Access to 800+ public-safety and law-enforcement customers
- 50+ patents supporting video, evidence management and analytics technology
- 122 open opportunities representing approximately $34 million in potential first-year contract value
- New fleet analytics and VuLink patents expand CYCU's technology opportunity
The Share Buyback Remains a Major Signal
One of the more interesting developments for shareholders was Cycurion's August 17 announcement authorizing a $500,000 share repurchase program over the following 12 months.
Management stated that it believes Cycurion is "meaningfully undervalued" relative to the business it has built and its trajectory. Repurchases can be made in open-market transactions or other lawful methods, although they remain subject to market conditions, liquidity, financing restrictions and CFO approval. The company is not obligated to repurchase any specific amount.
It is important to distinguish this from insider buying. The $500,000 authorization is a corporate share-repurchase program, not necessarily an executive personally purchasing shares.
After reviewing the recent SEC-related ownership information available for CYCU, I do not find evidence of a new significant open-market insider purchase by a Cycurion executive or director in August. Recent filings include new officer ownership disclosures, but those do not themselves report a purchase transaction.
More on Colorado Desk
- ClearSight Therapeutics Receives NIH SBIR Phase I Award for Conjunctivitis and EKC Research
- Follow No One Entertainment Launches AI-Free Record Label & Global Broadcast Network
- Lunai Bioworks (N A S D A Q: LNAI) Takes Parkinson's Discovery to the Next Level With Exclusive Tanaist Agreement
- Revenue Optics Names Prat Patibandla Director of Growth Marketing
- Independent Autopsies Are Changing Civil Cases: Kansas City Forensic Explains Why Families Are Seeking Second Opinions
So, while there is currently a strong management confidence/buyback story, investors should not confuse that with a newly reported insider Form 4 purchase.
Q2 Financial Results Show the Margin Story Is Getting Real
Cycurion's August 14 financial results remain one of the most important developments of the year.
The company reported:
$3.8 million in Q2 revenue, beating Wall Street's $3.62 million consensus, while gross profit increased to $1.1 million. The resulting 29.1% gross margin was nearly five times the 6.1% margin reported in Q2 2025.
EPS of $(0.41) also beat the consensus estimate of $(0.56), net loss improved to $4.0 million from $5.3 million, and adjusted EBITDA loss improved to $1.4 million from $2.1 million. Net debt declined 28% year-over-year to $5.8 million.
For investors, that margin expansion could ultimately be more important than the relatively flat year-over-year revenue.
Cycurion is deliberately shifting toward higher-margin cybersecurity, managed services and strategic consulting, and management believes the financial results are beginning to demonstrate the benefits of that strategy.
The $54.6 Million Contract Remains a Game Changer
CYCU's largest contract ever remains another major pillar of the investment story.
The company secured a $54.6 million, 10-year award through a partnership with a Top-5 global consulting firm to modernize and securely operate a major state Health and Human Services system.
The contract is expected to generate more than $5 million in annual revenue, with work scheduled to begin in November 2026.
A decade-long agreement of this size gives CYCU considerably more revenue visibility and could also create opportunities for additional business with the agency and consulting partner.
Digital Ally Is More Than an Acquisition
The August 4 closing of the Digital Ally video-solutions acquisition significantly broadened Cycurion's reach.
The acquired business adds more than $5 million of annual revenue and over $1.2 million of EBITDA, while bringing more than 800 law-enforcement, municipal and public-safety customers into CYCU's ecosystem.
The strategic opportunity is the cross-selling potential.
These customers already depend on Digital Ally's video and evidence-management products. Cycurion can potentially add cybersecurity, managed services and other technology solutions around those systems.
The acquisition also brought a portfolio of 50+ patents, strengthening CYCU's position in video surveillance, digital evidence and public-safety technology.
New Patents Expand the Addressable Market
Cycurion has continued building its intellectual-property portfolio since the acquisition.
On August 18, the company announced a new patent covering fleet driver analytics, designed to track vehicles, connect incidents with video evidence and generate comparative driver-performance profiles. CYCU says the technology gives it an opportunity to pursue commercial trucking, logistics, delivery and corporate fleets in addition to its existing public-safety market.
More on Colorado Desk
- JEGS Launches Transformed Digital Commerce Platform Powered by PhaseZero
- Subject matter experts: Present your ideas at IISE Annual Conference 2027 in Louisville
- Cummings Graduate Institute Celebrates New Doctor of Behavioral Health Graduates
- Visit London Appoints The SEO Works for AI-First Search Strategy
- Inglewood Associates and Gordon Brothers Provide Update on Sale Process for 925 Euclid Avenue in Cleveland
On August 19, the company announced another patent strengthening its VuLink technology, which automatically activates and synchronizes multiple recording devices—including body cameras and vehicle cameras—during an incident.
Together, these developments potentially make the Digital Ally platform more valuable to CYCU's existing 800+ customer relationships while opening additional commercial markets.
Reverse Split and Nasdaq Situation
Cycurion also implemented a 1-for-8 reverse stock split, effective August 28, 2026, with the shares beginning split-adjusted trading under the existing CYCU symbol.
Management has described the move as a step intended to address Nasdaq's minimum-bid requirement rather than a change to the underlying business.
In its shareholder letter, CEO Kevin Kelly emphasized that the company's focus remains on expanding margins, reducing debt, growing government and commercial relationships and ultimately reaching break-even, profitability and a cash-positive operating position by Q2 2027.
A Growing Pipeline Adds Another Layer of Potential
The company's opportunity pipeline remains significant.
As of early August, CYCU reported 122 open opportunities representing approximately $34 million in potential first-year contract value, including approximately $11 million in late-stage opportunities. The company had already closed 41 new awards during 2026.
That pipeline, combined with the $54.6 million contract, Digital Ally acquisition and expanding public-sector relationships, gives CYCU considerably more forward visibility than it had at the beginning of the year.
The Bottom Line for Investors
Cycurion is becoming an increasingly interesting story because multiple pieces are improving at the same time.
The company is not simply adding revenue. It is attempting to improve margins, acquire EBITDA-producing businesses, build recurring government relationships, expand its intellectual property and cross-sell cybersecurity into a much larger installed customer base.
The $500,000 buyback authorization adds a noteworthy vote of confidence from the Board, although investors should understand that it is not the same thing as new insider open-market buying.
Meanwhile, the 29.1% gross margin, $54.6 million 10-year contract, ~$30 million revenue run rate, 800+ new public-safety customers, 50+ patents and $34 million potential contract pipeline provide CYCU with a substantially broader story heading into the final months of 2026.
The next major test is execution: converting the pipeline into revenue, integrating acquisitions, maintaining margin expansion, reducing losses and ultimately reaching the profitability target management has established.
For investors willing to follow a speculative small-cap cybersecurity company through that execution phase, $CYCU has certainly become a company worth watching closely.
For more information on $CYCU visit: www.cycurion.com
Media Contact:
Company Name: Cycurion, Inc. (N a s d a q: CYCU)
Contact: Kevin Kelly, Chairman & CEO
Email: info@cycurion.com
Phone: 888-341-6680
Country: United States
DISCLAIMER: https://corporateads.com/disclaimer/
Disclosure listed on the CorporateAds website
Source: CorporateAds
0 Comments
Latest on Colorado Desk
- Put Your Herd on Your Phone: Kiko Nation Makes Livestock Management Simple
- Colorado: What Pueblo Leaders Are Saying About the Pueblo Chile 2028 American Innovation Coin
- Future Intelligence Think Tank Surpasses 1,000 Members Exploring Human and Artificial Intelligence
- Governor Polis Highlights Colorado as a Leader in Education and Celebrates National Clean Energy Week in Washington, D.C.
- Colorado Springs: Deceased motorcyclist identified from September 2 crash on East Platte Avenue East of North Chelton Road
- Colorado Springs: Refunds being issued to drivers impacted by incorrect speed safety camera fines issued between July 21 and September 1, 2026
- Gary Bernstein Expands Media Leadership Role With Senior Strategic Advisor Appointment To Blacksun Private Equity
- Governor Polis Highlights Colorado's Advancements in Early Childcare at the Early Childhood Leadership Summit
- Governor Polis Announces that the Mosco Pueblo Chile Will Be on Colorado's 2028 American Innovation Coin
- Headline: House of Nova Paints Every Face in Gold at New York Fashion Week
- Can Government Operate Better Through Innovation?
- Michael H. Kaplan Advocates for Seriously Injured Colorado Workers Who Need In-Home Care
- Industry Study Finds Revenue and Retention Opportunities Across Jiu-Jitsu Schools
- Colorado Springs: City welcomes José Lopez-Nava as Municipal Court Administrator
- Icon Dental Unveils Dedicated Invisalign® Denver Service Page for Whole-Health & TMJ Treatment
- Infinity Infusion Solutions Named Finalist for D Magazine's D CEO 2026 Excellence in Healthcare Awards
- ImagiPortal Launches 3D Video Calls and Onchain IP Registration Ahead of Pre-Seed Funding Round
- Governor Polis Takes Executive Action to Protect and Support Colorado Pollinators
- FEMA Releases Funding for Public Assistance and Hazard Mitigation Grants for Colorado, Some Dating Back to 2013
- Andrew-Thomas Contractors Launches Enhanced Safety Bollards Resource for Denver Metro Businesses